In the advent of unprecedented stages of load-shedding, most businesses and households have resorted to alternative sources of power for their day-to-day requirements. Given the astronomical initial capital investment in either Renewable or Non-Renewable sources of energy, it would be prudent to afford tax experts like MaxProf the opportunity to assist you in maximising on all the tax incentives meant to cushion business from this crisis.
Accelerated Depreciation Allowance
As from 1 March 2023, Section 12B of the of the Income Tax Act, allows individuals and companies to claim a 125% depreciation allowance on the cost and installation of any renewable energy. This means the taxpayer will save up to 27% of their initial cost of their power source through a reduction of their taxable income. Should the company have made a loss, the tax benefit can be carried over to the next financial year as a deferred tax asset.
A company procures a Solar System for R 230,000 (VAT inclusive); as from 1 March, they are entitled to the following:
- 15% input VAT = R 30,000 (provided they are registered for VAT)
- Tax deduction of 125% = R 250,000
- Income tax saving of R 67,500
Solar Panel Incentive for Individuals
This incentive allows individuals to claim a rebate to the value of 25% of new and unused solar photovoltaic panels, up to a maximum of R 15,000.
If a taxpayer purchases 15 solar panels at R 3,000 each (total cost R 45,000), they would be able to claim 25% of the cost, which is R 11,250. If the taxpayer had purchased 25 panels (total cost R 75,000) their claim would be limited to R 15,000.
Diesel Rebates
In his budget speech of 2023, the Minister of Finance announced an extension of the diesel refund scheme to the food-processing sector as a form of relief from load-shedding. The extension will apply from 1 April 2023 to 31 March 2025 and will be granted to taxpayers who meet the following requirements:
- The food-processor must be a registered VAT vendor
- The food-processor must be registered for diesel refunds
- The fuel purchase must be an “eligible purchase”
It was an expectation that a similar rebate to the existing “diesel rebate” would be extended to the manufacturers of foodstuffs but the draft amendments ONLY allow for 80% refund of the RAF levy.
Conclusion
It is important to note that these incentives are subject to change, and it is always a good idea to consult with a tax professional or financial advisor for advice when claiming tax deductions or other incentives.
Author:
Cedric Mataka
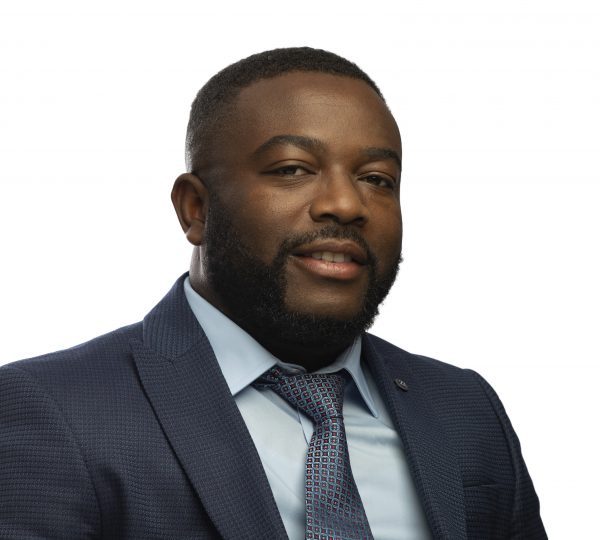
Author of article, “Combatting load-shedding through SARS Tax Incentives”, Cedric Mataka.